
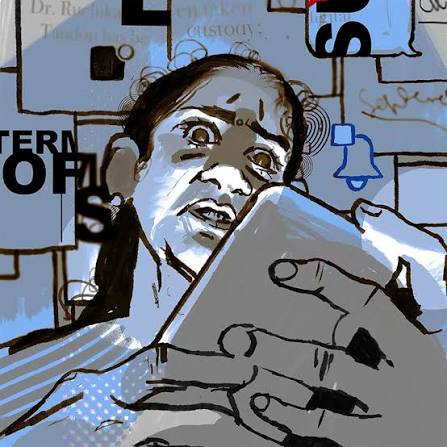
India is grappling with a sophisticated wave of “digital arrest” scams, where fraudsters impersonate law enforcement or government officials via video calls to coerce victims into paying large sums under the threat of arrest. These scams have evolved into a systemic crisis, leveraging the psychological pressure of authority and the ubiquity of messaging apps to siphon off life savings from unsuspecting citizens.
The Supreme Court of India has stepped in to address this void in security, recently directing major intermediaries, including WhatsApp, to submit detailed action plans to curb these crimes. The Court is not only demanding these plans be presented to the judiciary but also to the Indian Cyber Crime Coordination Centre (I4C), signaling a move toward a more integrated government-platform defense strategy.
WhatsApp has already attempted to demonstrate its commitment by reporting the ban of over 9,400 accounts during a targeted enforcement drive in early 2026. The platform is working on software updates designed to detect suspicious patterns and provide real-time warnings to users who may be targeted by impersonators. However, the company maintains that platform-level bans are insufficient, as criminals quickly rotate accounts and operate from overseas.
The judiciary is now pushing for a paradigm shift from reactive account-blocking to proactive prevention. By demanding an “action plan,” the Court is signaling that the burden of security must shift toward the platforms that facilitate these interactions. This puts pressure on tech giants to innovate better identity verification and fraud-detection algorithms that can recognize scam scripts before a victim is compromised.
Parallel to the crackdown on platforms, the Supreme Court has also targeted the financial side of these scams. The Court has directed banks to implement stricter safeguards and, crucially, to provide compensation to victims in cases where the financial institution’s own lack of due diligence enabled the fraud. This move transforms banks from passive pipes for money transfers into active gatekeepers of consumer funds.
This judicial push aligns with a broader shift in the Reserve Bank of India’s (RBI) regulatory approach. The RBI has introduced directions on “Responsible Business Conduct,” which aim to hold banks accountable for failures in electronic banking security. This marks a departure from the traditional view that the customer is solely responsible for any authorized transaction, even those made under duress.
Under these emerging RBI guidelines, a new framework for customer compensation is being established. In certain qualifying cases of fraud or coercion, banks may be required to compensate victims, potentially offering a one-time payment (reported around ₹25,000) for losses up to a specific threshold, provided the victim reports the incident within a strict window—typically five days.
However, the implementation of these financial protections remains complex. While the goals are ambitious, some reports suggest the full operationalization of these compensation frameworks may not be complete until January 1, 2027. This gap between the judicial demand for immediate action and the regulatory rollout leaves a window of vulnerability for current victims.
The combined pressure from the Supreme Court and the RBI creates a “pincer movement” against cybercriminals. By attacking both the communication channel (WhatsApp) and the payout channel (the banks), the Indian state is attempting to make the digital arrest business model too expensive and risky for the fraudsters to maintain.
Ultimately, the success of these measures will depend on the speed of technical execution and the willingness of banks to accept liability. While software updates and compensation caps are helpful, the fight against digital arrests requires a sustained effort in public awareness to ensure citizens know that no legitimate law enforcement agency ever conducts an “arrest” via a WhatsApp video call.